 Quick Pay


-

TVS Credit
-

Two Wheeler Loans
-

4 November, 2026
Summary
As Diwali approaches, so do financing offers, vehicle deals and more flood the market. Most finance lenders feature high downpayment funding, attractive interest rates to get as a key benefit to avail their Diwali offer. Expect to hear a lot about zero down payment options this Diwali season when looking to finance an electric scooter purchase using EV Loans. So, before you prepare to choose one, understand what zero down payment electric scooter loan really means.
What does zero down payment mean for an electric scooter?
Zero down payment for an electric scooter simply means you do not have to pay any upfront cost* at the time of purchase. While a traditional Two Wheeler Loan mostly finances up to 95%* of the scooter’s on-road price, a zero down payment loan promises 100%* financing.
What this means for you is that you pay nothing at the dealership, except for any applicable charges, and can take your electric scooter home without waiting to save for a down payment. You get to pay back the scooter’s on road price through EMIs over the selected repayment tenure.
Actual terms for electric scooter zero down payment depend on your credit profile and specific lender, and may involve additional charges like processing fees.
What is a down payment on an electric scooter?
Down payment is the upfront amount you pay when buying an electric scooter on a loan. Based on the electric scooter finance terms, you may need to pay an electric scooter down payment for the vehicle. The remaining balance can be financed with the Two Wheeler Loan.
Suppose you find a Diwali deal offering 95% financing on a ₹1,00,000 electric scooter. This broadly means you pay a 5% EV down payment of ₹5,000, while the remaining ₹95,000 can be covered by the loan. This calculation is for illustrative purposes only and should be used as a general guide.
Imagine you choose to make a 20% down payment of ₹20,000 instead. This will reduce your loan principal to ₹80,000, lowering your total interest/charges over the tenure. Increasing your downpayment means lowering your financed amount. Depending on tenure, interest rate, and other factors, it leads to potentially lower EMIs and reduced total repayment.
Zero down payment vs down payment: Key differences
There is a possibility you might wonder why zero down payment vs down payment is such a big deal during your festive electric vehicle purchase. Understand that choosing one of the two affects your overall financial planning with electric scooter EMIs and total borrowing costs. During a time when you need funds to plan your festive expenses, choosing a smart downpayment option can help navigate your festive preparation easily.
Below is the EV finance comparison based on down payment:
| Features | Zero Down payments | Down Payments |
| Upfront payment | Zero to minimal based on applicable charges | Required based on borrower’s profile |
| Financed amount | Generally higher | Generally lower |
| Monthly EMI | Usually higher as borrowed amount is higher | Usually lower because of lower borrowed amount |
| Overall Repayment | Could be higher due to a larger loan balance. | Could be lower as loan balance is smaller |
This table is for illustrative purposes only and should be used as a general guide.
For your festive upgrade with an electric scooter, compare both options to choose a financing deal based on your budget, savings, repayment capacity, among other factors.
How Down Payment Affects Your Festive Electric Scooter EMI?
Let’s see how a down payment can impact your electric scooter EMI. Fundamentally, keep in mind that making a down payment means you are left with a lower purchase amount to take a loan for. A higher down payment results in a lower loan principal, which potentially lowers your EMIs.
For a ₹1,00,000 electric scooter with zero down payment, your financed amount becomes ₹1,00,000. Let’s assume an annual interest rate of 12% for 24 months.
Using the standard reducing balance formula,
EMI = P x R x (1 + R)N ÷ [(1 + R)N – 1]
Monthly EMI is estimated to be ₹4,707.
Over the 24-month tenure, you will pay a total of around ₹1,12,968 for your electric scooter.
Now, have a look at the situation where you decide to pay a down payment of ₹20,000 for your ₹1,00,000 electric scooter.
Financed amount = ₹1,00,000 – ₹20,000 = ₹80,000
If we assume the same interest rate and tenure as above,
Monthly EMI ≈ ₹3,766
Total Loan Repayment ≈ ₹3,766 x 24 ≈ ₹90,384
Total Cost of the Electric Scooter ≈ ₹90,384 + ₹20,000 ≈ ₹1,10,384
Comparing both scooter EMI options, choosing the down payment option saves you approximately ₹941 per month and ₹2,584 in total purchasing cost.
Here is the side-by-side comparison:
| Factor | Zero Down payments | Down Payments |
| Purchase price | ₹1,00,000 | ₹1,00,000 |
| Down Payment | ₹0 | ₹20,000 |
| Financed amount | ₹1,00,000 | ₹80,000 |
| Annual interest rate | 12% | 12% |
| Tenure (months) | 24 | 24 |
| Estimated EMI | ₹4,707 | ₹3,766 |
| Total repayment | ₹1,12,968 | ₹90,384 |
| Overall Scooter Purchase Cost | ₹1,12,968 | ₹1,10,384 |
Disclaimer: Illustrative calculations. May vary with specific financing terms.
When zero down payment on Diwali purchase be useful?
The festive season brings the urge to shop more, and it is easy to overspend if you are not careful. Look at your fixed monthly expenses, including rent, groceries, utilities, and existing debt. If you have stable income and enough savings to support these liabilities, you can consider a down payment. However, if you do not want to disrupt your savings and can afford the resulting EMIs, an EV loan without down payment might be a useful financing option for you.
A zero down payment EV can be worth considering if:
- You have large upcoming expenses, including buying a home, funding higher education, and traveling.
- Diwali itself is an expensive time of year. Whether you are planning to buy new clothes, renovate your home, buy new appliances or gifts, you need to keep cash handy for the festivities.
- If you want immediate cash savings with lower upfront spending to improve your cash flow management.
- If you have a stable monthly income, which can manage both your fixed expenses and new EMI load.
A zero down payment usually means financing a larger amount. So, the real question is, can you afford the monthly EMIs and total repayment amount?
When Down payment on Diwali EV scooter be considered?

It is pretty clear that zero down payment helps a lot when you do not have enough cash on hand for an electric scooter. But what if you have enough savings for upfront contribution?
A down payment is a sensible choice if you have a stable income and sufficient savings that align with your financial goals. As pointed earlier, a larger down payment could reduce both your monthly EMIs and total repayment amount. This is largely possible because a higher down payment reduces the loan principal, which effectively lowers the total interest and associated charges. However, the actual figures are subject to applicable financing terms.
A down payment is a practical choice in the following cases:
- If you have enough savings to make the down payment.
- If you do not want higher EMI obligations for a long term.
- If you want lower overall cost, including total interest paid.
How to Choose Between Zero Down Payment and Down Payment This Diwali?
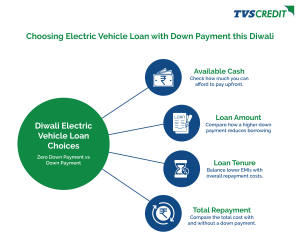
Heading into Diwali 2026 with a clear understanding of zero down payment versus traditional down payments will ensure a successful festive purchase. Do not make the mistake of falling to the marketing hype. Compare multiple finance offers to choose what works best for your finances. Before making a choice between zero down payment and down payment
Available cash
Evaluate how much cash is easily available for making the down payment.
Financed amount
Determine how much you want to borrow. Higher down payment translates to lower principal, which may reduce your EMIs and total borrowing cost.
Tenure
Compare EV Loan options across different tenures. A longer tenure could lower your EMIs but may increase overall repayment.
Total repayment
Evaluate scooter EMI options based on the vehicle’s true cost and compare total repayment amounts with and without a down payment.
After cross-checking these factors, your final choice will likely depend on your financial situation and repayment capacity. No guesswork; just a true picture of your finances and overarching need.
Diwali electric scooter offers: What should you check?
Do not let all the Diwali electric scooter offers overwhelm you and cloud your judgment. A zero down payment deal might appear attractive, but it does not tell the complete story. A wrong choice can haunt you throughout your tenure and beyond. Keep it simple and go through the following checklist before making a final choice:
- Check your eligibility for the EV Diwali offers to see which one matches your criteria and chosen electric scooter.
- Review the applicable charges on the scooter offer, as these fees increase the total cost of borrowing.
- Ensure that the repayment tenure aligns with your ability to pay back the loan.
- After determining how much you need to finance and for how much time, take a look at evaluated EMIs. Make sure it does not stretch your monthly budget.
- Calculate how much the electric scooter will truly cost after you finish paying off your loan.
Diwali offers for electric scooters can make owning an electric scooter easy. But to opt for a loan with zero down payment or choosing an EV Loan with maximum on road funding depends on your financial and repayment capability. Here’s to sustainable commuting and a brighter Diwali.
FAQs
1. What does zero down payment mean when buying an electric scooter?
Zero down payment means you do not pay upfront down payment, other than applicable charges, when buying an electric scooter.
2. Does zero down payment mean I do not have to pay anything upfront?
No, zero down payment does not mean you do not have to pay any cash up front. Based on the financing terms, you may have to cover processing fees, taxes, or other charges.
3. How does a down payment affect my electric scooter EMI?
A down payment directly impacts the financed amount, which usually determines your monthly EMIs.
4. Does paying a higher down payment reduce the EMI for an electric scooter?
A higher down payment reduces your loan principal, which may potentially lower your electric scooter EMI.
5. Is zero down payment available for every electric scooter?
Zero down payment may not be available for all electric scooters. Its availability may depend on brand deals and other festive offers. Some lenders like TVS Credit roll out Diwali Offer with 95% on road funding so that you get maximum loan amount.
6. What should I consider before choosing zero down payment for an electric scooter?
Before choosing a zero down payment option for an electric scooter, evaluate your eligibility, financed amount, EMI, tenure, total repayment, current savings, and future financial goals.
7. Does zero down payment mean there are no other financing charges?
No, zero down payment may still levy additional charges, including processing, documentation, taxes, among others.
8. Can I buy a smartphone on EMI if I already have other EMIs?
Yes, you can buy a smartphone on EMI even if you already have other EMIs subject to lender’s terms, your eligibility, and credit profile.
DISCLAIMER: While we ensure the information, products and services we offer through our website and associate platforms are accurate, there may be unintended inaccuracies and/or typographical errors in the content. The information on this site and related websites is for general informational purpose and in case of any inconsistencies, the details mentioned in the product/service document will take precedence. Viewers and subscribers are encouraged to seek professional advice and go through the product/service documents to make an informed decision before availing of a product or service.
*Terms & Conditions Apply – wherever applicable
- Share It On


Categories
Popular Blogs


Get Hassle-free Loan for all Your Financial Needs
Download the TVS Credit App for Easy Loan Process
Related Articles

Two Wheeler Loans
-
TVS Credit
-
22 October, 2026
How to pick the best Diwali electric scooter financing offer
Two Wheeler Loans
-
TVS Credit
-
22 October, 2026
Two Wheeler Loans
-
TVS Credit
-
12 October, 2026
How to reduce your Two Wheeler Loan EMI: 7 Smart Tips to lower Bike Loan EMIs
New on TVS Credit
Two Wheeler Loans
-
TVS Credit
-
4 November, 2026
Mobile Loans
-
TVS Credit
-
22 October, 2026
Two Wheeler Loans
-
TVS Credit
-
22 October, 2026
How to pick the best Diwali electric scooter financing offer